Futures Replay · Backtesting · Walk-Forward Validation해외선물 Replay · Backtest · Walk-Forward
Train your decisions on real markets. Validate your strategy on unseen data. 판단은 실제 시장에서 훈련하고, 전략은 실데이터로 검증하세요.
BTReplay replays real futures market data bar by bar so you can practice trading decisions, then evaluates the same strategy through backtesting and walk-forward validation.Strategy selection and final evaluation are kept separate, while every parameter and execution setting remains traceable. BTReplay는 실제 해외선물 데이터를 한 봉씩 재생해 매매 판단을 훈련하고, 동일한 전략을 백테스트와 워크포워드 검증으로 평가합니다.전략을 선택하는 구간과 최종 성과를 평가하는 구간을 분리하고, 모든 파라미터의 출처와 실행 조건을 기록합니다.
1H
Decision Timeframe의사결정 기준봉
3
3-Stage Walk-Forward워크포워드 3단계
0.5–8×
Replay Up to 8×Replay 최대 8×
Session complete세션 종료
Expectancy per Trade거래당 기대값
Number of Trades거래 횟수
Break-Even Win Rate손익분기 승률
You're on the list. We'll email you when your access becomes available.신청이 완료되었습니다. 참여 가능한 순서가 되면 이메일로 알려드리겠습니다.
The full product replays real market data and applies the same trading rules across backtesting and walk-forward validation.
Join early access to experience the complete BTReplay workflow.제품에서는 실제 시장 데이터를 Replay하고, 동일한 규칙으로 Backtest와 Walk-Forward 검증을 실행합니다.
얼리 액세스를 신청하고 BTReplay의 전체 기능을 먼저 경험해보세요.
Please tick the consent box to continue.수신 동의에 체크해 주세요.
We couldn't submit that. Check the address and try again.신청이 처리되지 않았습니다. 주소를 확인해 다시 시도해 주세요.
This demo runs on sample data generated in your browser. The full product replays connected real market data.
Shortcuts: B Buy · S Sell · X Close · Space Pause현재 데모는 브라우저에서 생성한 샘플 데이터로 동작합니다. 정식 제품에서는 연결된 실제 시장 데이터를 Replay합니다.
단축키: B 매수 · S 매도 · X 청산 · Space 일시정지
01 — The problem문제
Making the numbers look good is not the same as building a good strategy.
좋은 숫자를 만드는 것과
좋은 전략을 만드는 것은 다릅니다.
When parameters are optimized on the full dataset and performance is measured on that same data, the results will naturally look better.A strategy with only a handful of trades may rank above one backed by a meaningful sample. And when both a stop and target are touched within the same bar, a single execution assumption can change the outcome. 전체 데이터에 맞춰 파라미터를 조정한 뒤 같은 데이터로 성과를 측정하면 결과는 자연스럽게 좋아집니다.거래 횟수가 지나치게 적은 전략이 우연히 최상위에 올라갈 수도 있고, 한 봉 안에서 손절과 목표가가 모두 체결 가능한 상황에서는 작은 체결 가정 하나가 결과를 바꿀 수도 있습니다.
These problems rarely trigger an error.
They simply make the backtest look better than it really is.
이런 문제는 오류 메시지를 만들지 않습니다.
대신 백테스트 결과를 실제보다 더 좋아 보이게 만듭니다.
The strategy did not suddenly break. The parameters were simply fitted to conditions that no longer exist.전략이 갑자기 망가진 것이 아닙니다. 과거 데이터에 맞춰진 값이 새로운 시장에서는 더 이상 통하지 않는 것입니다.
02 — Validation structure검증 구조
Separate the data used to choose a strategy from the data used to judge it.
전략을 고르는 데이터와
전략을 평가하는 데이터를 분리합니다.
Each fold searches for candidate strategies on the training set, selects one on the validation set, and only then evaluates it on the test set.Thresholds are recalculated using only the training window of each fold. They are never derived from the entire dataset and reused as if they were out-of-sample.The test set remains sealed until final evaluation.
Once you inspect it and adjust the strategy based on what you saw, it is no longer truly out-of-sample.
각 Fold에서 Train 구간으로 후보 전략을 탐색하고, Validation 구간에서 하나를 선택한 뒤에야 Test 구간에서 최종 평가합니다.전략의 임계값 역시 각 Fold의 Train 데이터만으로 다시 계산합니다. 전체 데이터를 한 번에 사용해 값을 만든 뒤 테스트에 적용하지 않습니다.Test 구간은 최종 검증 전까지 열지 않습니다.
한 번 확인한 Test 결과를 보고 다시 파라미터를 수정했다면, 그 구간은 더 이상 완전한 Out-of-Sample 데이터가 아닙니다.
03 — What we prevent무엇을 막는가
No hidden assumptions. 숨겨진 가정을 남기지 않습니다.
A backtest is trustworthy not because the results look good, but because every assumption behind those results can be identified and explained. 백테스트의 신뢰성은 결과가 얼마나 좋아 보이는지가 아니라, 어떤 가정과 조건으로 만들어졌는지를 얼마나 명확하게 설명할 수 있는지에 달려 있습니다.
| Validation control검증 장치 | What it prevents방지하는 문제 |
|---|---|
| Three-Stage Walk-Forward3단계 Walk-Forward | Prevents strategy selection and final evaluation from using the same data전략 선택과 최종 평가에 같은 데이터를 사용하는 문제 방지 |
| Sealed Test SetTest 봉인 | Prevents tuning a strategy after inspecting test resultsTest 결과를 본 뒤 해당 구간에 맞춰 전략을 다시 조정하는 문제 방지 |
| Per-Fold RecalculationFold별 재계산 | Prevents thresholds calculated on future data from leaking into the test전체 데이터를 이용해 계산한 임계값이 미래 정보로 유입되는 문제 방지 |
| Minimum Sample Threshold최소 표본 기준 | Prevents tiny samples from dominating strategy selection지나치게 적은 거래로 만들어진 우연한 결과 방지 |
| Parameter Provenance파라미터 출처 기록 | Prevents undocumented parameters from being treated as validated inputs근거 없는 설정값이 검증된 값처럼 사용되는 문제 방지 |
| Run Fingerprint실행 지문 | Preserves the exact data and configuration behind every result결과만 남고 실행 당시 데이터와 설정을 잃어버리는 문제 방지 |
| One-Minute Replay Check1분봉 재생 검증 | Resolves ambiguous stop/target sequences with lower-timeframe replay같은 봉에서 손절과 목표가가 모두 닿았을 때 임의의 체결 순서를 가정하는 문제 방지 |
| End-of-Period Handling구간 종료 처리 | Prevents open positions from silently disappearing at the end of a test테스트 종료 시점의 미청산 포지션이 결과에서 누락되는 문제 방지 |
04 — Features주요 기능
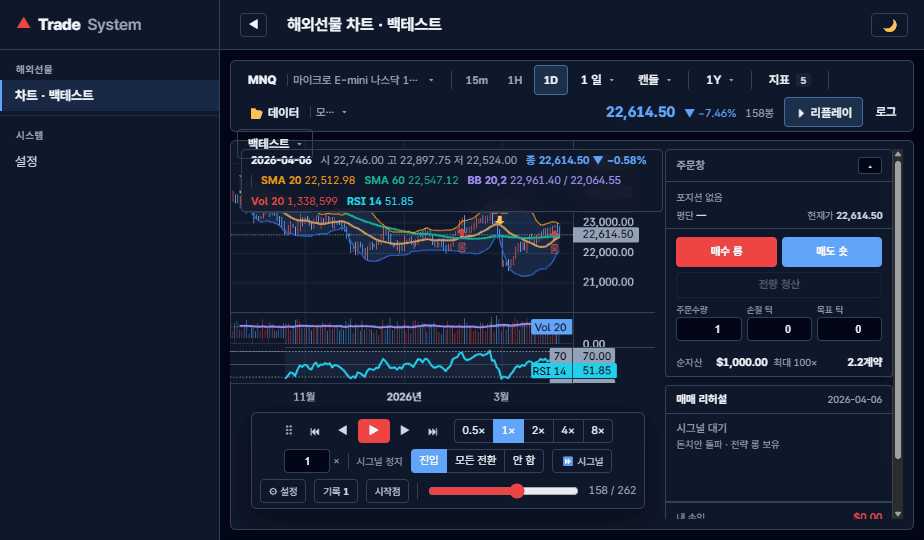
Real-Market Replay Training실데이터 Replay 훈련
Replay real market sessions from 0.5× to 8× speed, or advance the market one bar at a time.Practice entries, exits, stops, targets, and trade review directly alongside the chart.실제 시장 세션을 0.5×부터 8×까지 원하는 속도로 Replay하거나 한 봉씩 직접 진행하세요.주문, 손절, 목표가와 매매 기록을 차트와 함께 확인하며 실제 시장처럼 판단을 반복할 수 있습니다.
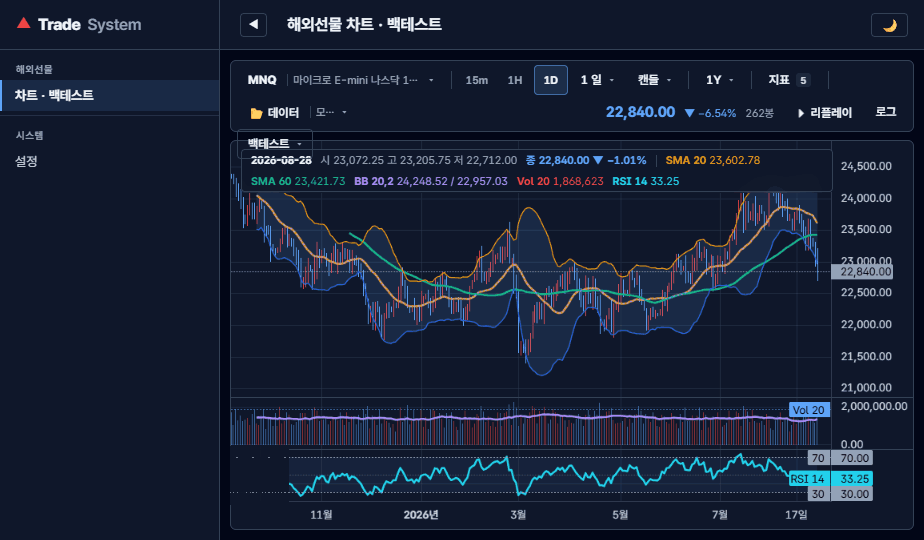
Charts & Indicators차트와 지표
View the same market series across 15-minute, 1-hour, and daily timeframes.Moving averages, bands, volume, and oscillators use the same calculations in both the interface and the strategy engine.하나의 시계열을 15분, 1시간, 1일 차트로 전환할 수 있습니다.이동평균, 밴드, 거래량, 오실레이터는 화면과 전략 엔진이 동일한 계산 로직을 사용합니다.
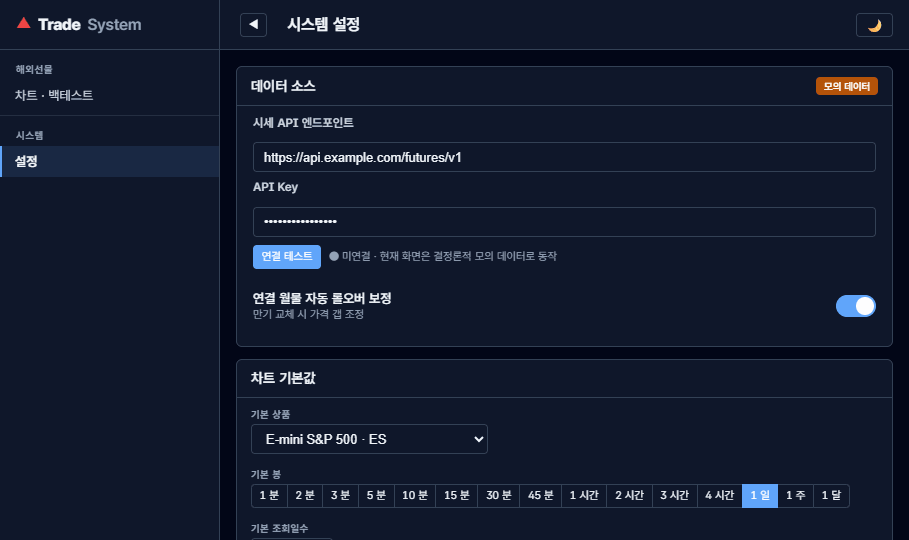
Data Sources & Contract Rollover데이터 소스와 롤오버
Connect your own market data source or work with the provided sample data.Continuous-contract rollover and price-gap adjustments are handled as explicit settings rather than hidden transformations.사용 중인 시장 데이터 소스를 연결하거나 제공되는 샘플 데이터로 테스트할 수 있습니다.연속 월물의 롤오버와 가격 갭 보정은 자동으로 숨겨 처리하지 않고 명확한 설정으로 관리합니다.
Screens from the current build. Sample data shown.현재 빌드 화면입니다. 표시된 데이터는 샘플입니다.
Train your decisions with Replay. Validate your strategy with data. Replay로 훈련하고, 데이터로 검증하세요.
BTReplay's private beta will open in stages.Leave your email and we'll send you an invitation when access becomes available, along with essential product updates. BTReplay 비공개 베타는 순차적으로 오픈합니다.이메일을 남겨주시면 참여 가능한 시점에 초대장과 주요 제품 업데이트를 보내드립니다.
You're on the list. We'll email you when your access becomes available.신청이 완료되었습니다. 참여 가능한 순서가 되면 이메일로 알려드리겠습니다.
Please tick the consent box to continue.수신 동의에 체크해 주세요.
We'll email you when access opens. Unsubscribe anytime.베타 참여가 가능해지면 알려드립니다. 언제든 수신을 거부할 수 있습니다.
We couldn't submit that. Check the address and try again, or write to admin@btreplay.com.신청이 처리되지 않았습니다. 주소를 확인해 다시 시도하시거나 admin@btreplay.com으로 보내주세요.